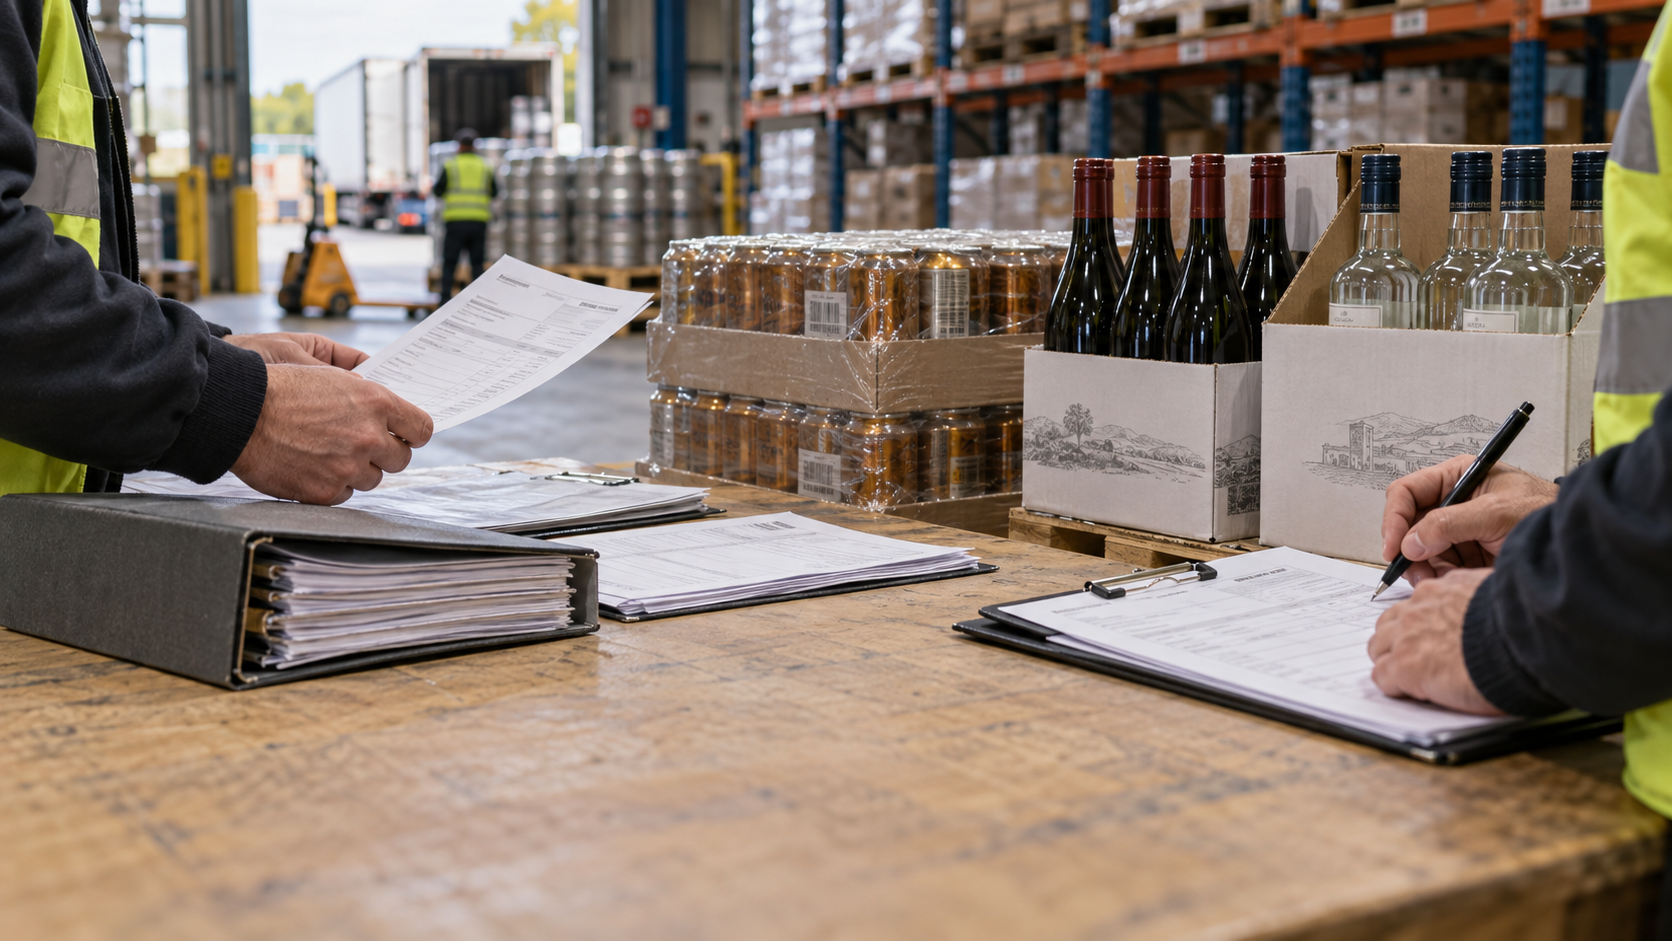
Alcohol stock needs evidence that the supplier is legitimate, the product has moved through the right duty route and your own checks were done before you bought it. In most UK business-to-business alcohol chains, the practical question is not whether you can show a single “customs duty paid” certificate. It is whether your records prove that excise Alcohol Duty risk was checked, that the wholesaler was approved where approval was required, and that invoices, delivery notes and stock records all describe the same goods.
HMRC’s Alcohol Wholesaler Registration Scheme (AWRS) is the central control for duty-paid wholesale alcohol. Excise Notice 2002 says AWRS applies to businesses selling, offering or arranging to sell alcoholic product to other businesses at or after the duty point, unless an exclusion applies. That means trade buyers need supplier approval evidence before doing business, not after HMRC asks questions.
The safest evidence pack is repeatable: a supplier AWRS unique reference number, a saved HMRC look-up result, an invoice showing the URN where required, delivery and stock records, a payment trail, and a short internal note showing what you checked. A clean pack does not remove every risk, but it gives your buyer, finance team and compliance lead the same audit trail.
Key Takeaways
- For UK duty-paid wholesale alcohol, AWRS approval evidence is usually more relevant than a generic customs duty receipt.
- HMRC says trade buyers must request the supplier’s AWRS URN and check its authenticity before doing business.
- Save or print the HMRC look-up result and keep it with the purchase file, supplier onboarding record or stock movement record.
- A supplier invoice is weak evidence if it does not connect the URN, legal entity, trading name, product, quantity and delivery route.
- Alcohol duty stamps should not be used as current proof that spirits are duty paid, because HMRC says the scheme has ended.
- Import, excise warehouse and duty-suspension movements need different documents from ordinary duty-paid wholesale purchases.
What Evidence Proves Alcohol Duty Has Been Accounted For?
Useful evidence shows a chain of accountability from supplier approval through to the stock received. The minimum file should identify who sold the goods, whether that business needed AWRS approval, what product was supplied, how much was supplied, when it moved, and how you paid.
For duty-paid purchases from a UK wholesaler, start with the supplier’s AWRS unique reference number. HMRC Excise Notice 2002 says approved wholesalers receive a URN, must provide it to customers, and must include it on wholesale sales invoices involving controlled alcoholic product. The number has to belong to the supplier you are actually dealing with.
HMRC also says trade buyers buying duty-paid alcoholic product from wholesalers for resale have had to check the supplier’s URN using the online look-up service since 1 April 2017. Keep the look-up result in a form you can retrieve later. A PDF print, screenshot, supplier onboarding note or compliance-system attachment can work if it records the name, URN, check date and person who performed the check.
The commercial paperwork still matters. Your purchase invoice should describe the product, quantity and price paid, and your goods-in record should show that the stock received matches the invoice. HMRC Notice 2002 says buyers should be able to evidence where alcoholic products were purchased, the quantity and price paid, with commercial documentation such as a purchase invoice.
Customs Duty, Alcohol Duty and VAT Are Different Checks
The phrase “customs duty payment evidence” can mislead teams handling alcohol. Customs duty is an import charge, Alcohol Duty is an excise charge on alcoholic products, and VAT is a separate tax. A domestic duty-paid wholesale purchase is normally tested through AWRS and excise due diligence, even if someone in the business loosely calls the file “customs proof”.
The distinction affects the documents you should ask for. A UK wholesaler selling duty-paid beer, wine, cider or spirits should be able to provide AWRS details where the scheme applies. An importer, customs agent or excise warehousekeeper may instead point to import declarations, warehouse release documents, duty accounting records or movement references, depending on when the goods left duty suspension.
Do not force every transaction into one document checklist. A first purchase from a UK wholesaler, a movement from an excise warehouse, and direct import of alcohol into free circulation create different risks. The records should explain how the goods reached duty-paid status and who controlled them at each stage.
This is similar to wider supply-chain record discipline. A customs team proving origin or import compliance has to connect declarations, invoices and transport records; an alcohol buyer has to connect supplier approval, stock movement and payment evidence. The same evidence mindset sits behind our guide to customs seizure and duty-proof records.
The Practical Evidence Pack
Build the file before the first order, then refresh it when supplier details change. Waiting until an invoice query, customer audit or HMRC visit leaves the team trying to reconstruct decisions from inbox searches.
For a UK duty-paid wholesaler, retain the supplier’s legal name, trading name, address, AWRS URN, VAT number if available, and the date you checked the URN on HMRC’s service. Add the saved look-up result and make sure the details match the supplier account in your finance system. If the trading name differs from the legal entity, keep a note explaining the connection.
For each order, keep the purchase order or buying instruction, invoice, delivery note, goods-in record and payment record. The invoice should show the AWRS URN where required, and the product description should be specific enough to match the stock received.
Stock records should show that cases, pallets or litres received moved into the correct site, bonded area or retail channel. If stock is split, transferred or returned, record the movement. Alcohol supply chains can become difficult to evidence when the initial purchase file is complete but later stock movements are informal.
Red Flags HMRC Expects You To Notice
Missing or inconsistent AWRS information is a major warning sign. HMRC’s due-diligence risk indicators include inability to confirm AWRS approval, no AWRS URN, a URN apparently belonging to a different wholesaler, and no valid pro-forma or purchase invoice. Those are not minor admin issues when the goods are alcoholic product being bought for resale.
Price is another control. If a supplier offers duty-paid alcohol at a price that looks too low for the product and channel, record how you challenged it. Current Alcohol Duty rates published by HMRC were last updated on 1 February 2026 and include, per litre of pure alcohol, £22.58 for beer from 3.5% to 8.4% ABV, £30.62 for beer from 8.5% to 22% ABV, and £33.99 for spirits stronger than 22%. Those rates make very low landed or wholesale prices worth questioning.
Payment and delivery patterns can also point to risk. Be cautious where a new supplier asks for payment to an unrelated account, refuses ordinary invoice information, routes goods through unexpected sites, or changes entity details after onboarding.
Your file should show the decision made at the time. If the buyer accepted an explanation, keep that explanation with the order. A later note saying “supplier confirmed all was fine” is much weaker than a dated record showing the question asked, the answer received, and the evidence checked before the goods moved.
Spirits And Duty Stamps
Do not rely on alcohol duty stamps as current proof. HMRC Notice 2002 has been updated to reflect the discontinuation of the Alcohol Duty Stamps Scheme, and HMRC says the presence or absence of a duty stamp is no longer a risk indicator by itself. Older habits around stamped bottles can therefore give teams false confidence.
For spirits, use the same evidence chain as other alcohol products: supplier approval where AWRS applies, invoice details, stock records and payment trail. If a bottle has a stamp, it may be part of the product’s history, but it should not replace supplier and transaction checks. If it lacks a stamp, that absence should not automatically stop the purchase without looking at the wider evidence.
This point matters for mixed loads. A pallet containing spirits, wine and beer may have inconsistent legacy markings, imported labels or packaging differences. The buyer’s control should be based on supplier legitimacy and transaction evidence.
Warehouse teams should still flag suspicious packaging, broken seals, mismatched labels or unexplained relabelling. Those observations belong in the same due-diligence file because they help explain why the goods were accepted, quarantined or rejected. A good process lets warehouse staff raise concerns before the invoice is paid.
Import And Warehouse Edge Cases
Goods under duty suspension need a different evidence trail from goods already duty paid. Alcohol may move under excise control through an approved warehouse or from overseas before duty is accounted for. In those cases, AWRS is only one part of the picture, and the file may need movement, warehouse or import evidence as well.
For imported alcohol, check how the goods entered the UK, who acted as importer of record, and when customs and excise liabilities were accounted for. Your file may need import declaration references, freight documents, duty deferment information, warehouse release evidence or a supplier statement linking those records to the stock sold to you.
If your business also handles import operations, keep the alcohol file aligned with your broader customs processes. Our UK customs clearance guide explains the declaration route, while the EORI guide covers the trader identity number used in customs processes. Those records do not replace AWRS checks for duty-paid wholesale purchases, but they help explain the import side.
Excise warehouse movements should be handled with particular care. Make sure the person releasing goods from duty suspension has the authority and records to do so, and keep evidence of the point at which the goods became duty paid. If your team cannot explain whether stock is duty suspended or duty paid, stop the transaction until the position is clear.
A Buyer Checklist Before The First Order
Ask the supplier for its legal name, trading name, address and AWRS URN before agreeing the first purchase. Check the URN on HMRC’s look-up service and save the result. Confirm that the name and address match the business offering the goods.
Review the first invoice before stock is released into saleable inventory. It should show the supplier details, product description, quantity, price and AWRS URN where required. If the invoice arrives after the goods, quarantine the stock until the missing paperwork is resolved.
Compare the delivery note and goods-in record with the invoice. Differences in quantity, product type or delivery route should be explained in writing. The explanation can be short, but it should be dated and linked to the order.
Keep the payment trail with the supplier file or make it easy to retrieve from finance. Payment to a bank account that does not match the supplier identity should be escalated before funds leave the business. This is both a fraud control and an excise due-diligence control.
Set a refresh cycle for active suppliers. Annual checks may be enough for stable low-risk suppliers, while high-volume or unusual suppliers may need more frequent checks. The point is to make AWRS and evidence review a live control rather than a one-off onboarding task.
Frequently Asked Questions
Is an invoice enough to prove alcohol duty has been paid?
An invoice helps, but it is rarely enough by itself. HMRC expects trade buyers to check AWRS approval where the supplier is a UK wholesaler selling duty-paid alcoholic product for resale. The invoice should connect to a valid URN, saved look-up result, delivery record and payment trail.
Do trade buyers have to check AWRS every time they order?
HMRC says buyers must request the wholesaler’s URN and check its authenticity before doing business. The law and guidance do not turn that into a simple “every order” rule for all situations, but repeat buyers still need a sensible refresh process. Recheck when supplier details change, when risk indicators appear, or when a dormant supplier becomes active again.
What happens if stock comes from an unapproved UK wholesaler?
HMRC Notice 2002 says that if stock is supplied by an unapproved UK wholesaler, HMRC may seize the stock, apply penalties of up to £10,000, or prosecute. That risk sits with the buyer as well as the supplier when the buyer failed to perform normal checks. Do not sell or distribute questionable stock while the evidence gap is unresolved. Escalate it to compliance, finance and senior management before making a commercial decision.
Are alcohol duty stamps still useful evidence?
Duty stamps should not be treated as current proof that spirits are duty paid. HMRC says the Alcohol Duty Stamps Scheme has been discontinued and that the presence or absence of a stamp is no longer a risk indicator by itself. Use supplier approval, invoices, delivery records, stock records and payment evidence instead. Packaging observations can still support a risk assessment, but they are not the core proof.
Does this apply to private consumers?
AWRS trade-buyer checks are aimed at business purchases for resale, not private individuals buying alcohol at retail for personal use. The controls matter for wholesalers, retailers, hospitality operators, marketplaces and other businesses buying stock. If a business buys alcohol only for staff events or internal consumption, the risk profile is different, but ordinary invoice and supplier checks still make sense. When in doubt, decide whether the transaction is part of a resale supply chain.
How long should the evidence be kept?
Keep alcohol purchase evidence in line with your tax, accounting and excise record retention policy. The important point is that the AWRS check, invoice, goods receipt, stock movement and payment record can be retrieved together. If different teams own different systems, add a reference number that links the records. A complete file is much more valuable than a perfect document stored where no one can find it.